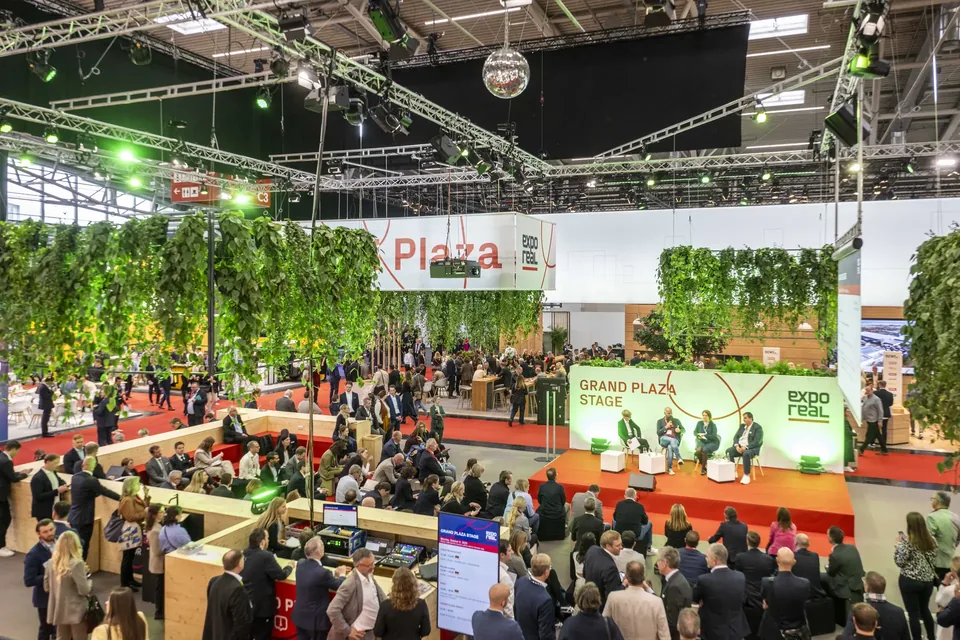
EXPO REAL opens with lenders keen but choosy, prices still under negotiation and projects waiting on terms, power and policy. This is the field guide to which of those can move in Munich.
At EXPO REAL, the investable question is increasingly about power, networks and the land that makes them possible. The constraint may be a grid connection, not a planning consent.
First look: RealTimes Market Intelligence. Every figure sourced. Every
source named. Learn more →
Warsaw, Silesia, Łódź and Wrocław each run their own stand in Hall A2. What that says about who sells Poland to international capital, and about who is buying.
Czechia brings one national exposition to Munich and a market driven by its own capital. Is Prague's tight yield a sign of depth, or a door outside buyers struggle to open?
Romania comes to Munich on a chamber-led stand with the widest prime office yield in one broker's CEE list. Is that a reward, or the price of thin liquidity?
Counter: Trades are closing anyway: German volume ran 15% ahead of last year in the first half, with 21 deals above €100m, so the conversation is already turning into trades.
Counter: National volume is up 15%, so the recovery is broader than a handful of postcodes.
RealTimes PeerViews
RealTimes PeerView
A confirmed conversation, not a crowded stand
A PeerView is a prepared, time-bounded exchange between two senior peers, curated and briefed by RealTimes ahead of EXPO REAL 2026. It is not a meeting slot, a pitch or a one-sided conversation. Sponsors and executives take part on different terms, and every match follows the same brief.
Two senior peers, selected to meet as equals
Both sides briefed in advance, on an agenda agreed before the conversation starts
Curated by RealTimes, the same standard behind the RealTimes PeerViews film series and RealTimes event stages
Six years after its 2019 record (five editions; 2020 was cancelled), EXPO REAL has 90% of its crowd and 80% of its exhibitors. After 2008, the stands never fell that far.
RealTimes desk
Last timeThe 2008 record of 1,856 exhibitors fell in 2017, nine editions later, with 2,003.
This timeExhibitors have fallen three editions running: 1,887, 1,856, 1,778, 1,742.
Rates are context, not causeIn the year to the 2023 fair the ECB raised its main rate from 1.25% to 4.50%, the steepest twelve months in the series. Exhibitors slipped 1.6%.
This fairOpens 5 Oct, 19 days after the ECB raised its main rate to 2.65%.
After the 2019 record: 2,189 exhibitors, 46,747 participants
After the 2008 record: 1,856 exhibitors, 42,000 participants
Both cycles count all participants, trade visitors plus exhibitor staff, so they compare like for like. The 2022, 2024 and 2025 participant totals are the organiser’s rounded figures. Sources: ECB key interest rates; EXPO REAL final reports and contemporary press, 1998 to 2025, linked edition by edition under “See the data”. From 28 Jun 2000 to 14 Oct 2008 the main rate is the minimum bid rate of variable-rate tenders.
Exhibitors and participants at each EXPO REAL as a share of the record edition, comparing the recovery after 2019 (2,189 exhibitors) with the recovery after 2008 (1,856 exhibitors). In 2025 the fair had 1,742 exhibitors, 80% of its record, against 89% at the same point after 2008. Participants reached 42,000, 90% of the record, against 88% last time. Last time exhibitors beat the 2008 record in 2017, 9 editions on, with 2,003. 2020 was cancelled and is shown as a gap. The ECB main rate on opening day ran from 4.25% down to 0.00% after 2008, and from 0.00% up to 4.50% after 2019; it is 2.65% as the 2026 fair opens.
See the data
Editions
1998 147 exhibitors, 2,528 trade visitors (retrospective count, organiser blog 2017). “What do we do if nobody comes?” The 1998 fair filled one hall at the M,O,C.Source
1999 324 exhibitors, 4,500 trade visitors; ECB 2.50% on opening day. “Almost exclusively good marks.”Source
2000 Figures not published. “Exhibitors and visitors are both highly content with the results.”Source
2001 900 exhibitors; ECB 3.75% on opening day. “In the real-estate industry's field of vision.”Source
2005 1,415 exhibitors, 18,000 trade visitors; ECB 2.00% on opening day. “Excellent mood in the halls.”Source
2006 1,638 exhibitors, 21,000 trade visitors; ECB 3.25% on opening day. “Record figures, driven by internationalisation.”Source
2007 1,823 exhibitors, 39,000 all participants; ECB 4.00% on opening day. “Breaks attendance record. Ten-year expansion through international demand.”Source
2008 1,856 exhibitors, 42,000 all participants; ECB 4.25% on opening day. “Growth despite the credit crisis.”Source
2009 1,580 exhibitors, 36,000 all participants; ECB 1.00% on opening day. “Back down to earth.”Source
2010 1,645 exhibitors, 37,000 all participants; ECB 1.00% on opening day. “The industry is on the up.”Source
2011 1,610 exhibitors, 37,000 all participants; ECB 1.50% on opening day. “An anchor of stability for the industry, despite turbulence on the financial markets.”Source
2012 1,700 exhibitors, 38,000 all participants; ECB 0.75% on opening day. “New record exhibitor numbers despite crisis.” (organiser's claim; 1,700 is below the 2008 peak)Source
2013 1,663 exhibitors, 36,000 all participants; ECB 0.50% on opening day. “Good mood, more concrete business and greater optimism than in recent years.”Source
2014 1,655 exhibitors, 36,900 all participants; ECB 0.05% on opening day. “International participation grows; positive investment and financing mood continues.”Source
2015 1,707 exhibitors, 37,857 all participants; ECB 0.05% on opening day. “Light growth.”Source
2016 1,768 exhibitors, 39,101 all participants; ECB 0.00% on opening day. “Europe has to stick together. Brexit was the principal discussion topic.”Source
2017 2,003 exhibitors, 41,775 all participants; ECB 0.00% on opening day. “Strong and watchful.”Source
2018 2,095 exhibitors, 44,536 all participants; ECB 0.00% on opening day. “Record results.”Source
2019 2,189 exhibitors, 46,747 all participants; ECB 0.00% on opening day. “Strong showing and upbeat expectations.”Source
2020 Cancelled. “Cancelled because of worsening COVID-19 conditions. Both the physical and digital parts were cancelled.”Source
2021 1,198 exhibitors, 19,200 all participants; ECB 0.00% on opening day. “New start successful.”Source
2022 1,887 exhibitors, 40,000 all participants; ECB 1.25% on opening day. “Real estate industry at a turning point.”Source
2023 1,856 exhibitors, 40,238 all participants; ECB 4.50% on opening day. “Room for reorientation amid uncertainty.”Source
2024 1,778 exhibitors, 40,000 all participants; ECB 3.65% on opening day. “Slight sense of confidence in a changing market.”Source
2025 1,742 exhibitors, 42,000 all participants; ECB 2.15% on opening day. “Provides impetus. Cautious optimism. The industry is focusing on the future.”Source
How to read this chart. Participants were counted as trade visitors only from 1998 to 2006 and as all participants, trade visitors plus exhibitor staff, from 2007, so the 2006 to 2007 jump is partly a change of definition, not growth. 2020 was cancelled: the gap is a missing edition, not zero. 2002 figures are pre-show registrations. Countries means participant or visitor countries; exhibitor countries are shown only where the source publishes them. Each mood line is taken from that edition's final report or a contemporary press account, in English. The 2026 edition runs 5 to 7 Oct and has no figures yet.
18 open calls. Fund manager (3) · Senior lender (4) · Valuer (1) · Broker (3) · Debt fund manager (1) · Developer (2) · Operator (1) · City & public sector (2) · Investor (1)
Fund manager · Europe
Fund manager, Europe
For a stabilised office or logistics asset in a city you are active in, what entry-yield range would you bid this week, and how has that range moved since EXPO REAL 2025? Ranges are fine.
On a €50m, five-year senior loan against a stabilised, EPC-A Munich office, what LTV and margin would you quote this week, and what changes at EPC-D with no capex plan? Ranges are fine.
For a Grade A office asset you are currently valuing, what is the live gap between your bid-side and ask-side, in basis points or as a percentage, and has it narrowed since the ECB's 10 Sep rate decision? Ranges are fine.
Of the live mandates on your desk at EXPO REAL (5 to 7 Oct), roughly what share have moved from an indicative guide price to a signed bid rather than staying a conversation? Ranges are fine.
What is the longest loan duration your vehicle is writing this year, one to three years, three to five, or longer, and is that capped by your own fund's termination date rather than the borrower's ask?
For a stabilised office or logistics asset in a city you are active in, what entry-yield range would you bid this week, and how has that range moved since EXPO REAL 2025? Ranges are fine.
Which German city's investment and vacancy numbers are you underwriting against this quarter, not the national average, and by how many percentage points do they diverge from the Big 7 figures?
What yield gap over Warsaw, in basis points, would you need before underwriting a Bucharest asset this quarter, and has that required gap widened or narrowed since the ECB's 10 Sep rate decision?
On a €50m, five-year senior loan against a stabilised, EPC-A Munich office, what LTV and margin would you quote this week, and what changes at EPC-D with no capex plan? Ranges are fine.
On a €50m stabilised logistics asset refinancing this quarter, what margin over the ECB's main refinancing rate would you quote, and what changes if the asset misses a sustainability screen? Ranges are fine.
On a Frankfurt office refinancing this quarter, what margin would you quote in basis points, and how does it compare with the same asset type in Hamburg or Munich? Ranges are fine.
On a Bratislava office loan this quarter, what loan-to-value would you write compared with an equivalent Prague asset, and is that priced independently of Czech risk?
For a Grade A office asset you are currently valuing, what is the live gap between your bid-side and ask-side, in basis points or as a percentage, and has it narrowed since the ECB's 10 Sep rate decision? Ranges are fine.
Of the live mandates on your desk at EXPO REAL (5 to 7 Oct), roughly what share have moved from an indicative guide price to a signed bid rather than staying a conversation? Ranges are fine.
Of this year's Prague office deals you have closed, roughly what share had a buyer from outside CEE, and is that share rising or falling versus last year?
What is the longest loan duration your vehicle is writing this year, one to three years, three to five, or longer, and is that capped by your own fund's termination date rather than the borrower's ask?
For your most advanced data-centre site, what is the confirmed energisation date and current grid-queue position, and who carries the risk in your contracts if that date slips?
Of the equity behind your last three deals, roughly what share came from outside Central and Eastern Europe, and has that share risen or fallen over the past year?
For your next greenfield data-centre project, is the power supply contracted, in queue, or still unaddressed, and how many kilometres from the nearest established hub does the site sit?
Across the Polish city stands you have visited this week, which one gave you the most specific, site-level pitch, and what made it more concrete than the others, in two sentences?